Get approved · then go find your home
Get approved, then go find your home
Getting pre-approved means a lender has reviewed your finances and told you, in writing, the loan amount you qualify for. It is the first smart step when buying in Bethany and Oak Hills, because sellers and listing agents take pre-approved buyers seriously. Your offer is one step closer to closing before it is even written. Travis Olson of Eureka Mortgage Planning is our mortgage partner for buyers here, and once your documents are in he can typically tell you your number fast.
Our mortgage partner
Want to talk to Travis Olson, Eureka Mortgage Planning?
Travis is our trusted mortgage partner for buyers in Bethany and Oak Hills. As Northwest Area Manager at Eureka Mortgage Planning, he works with a network of national and boutique lenders, which means he can match buyers with the right program rather than funnelling everyone into one loan. He guides buyers through pre-approval, eligibility and the paperwork with plain-English explanations and straight answers. He answers his own email, and all contact for him goes to:
tolson@eurekamortgage.net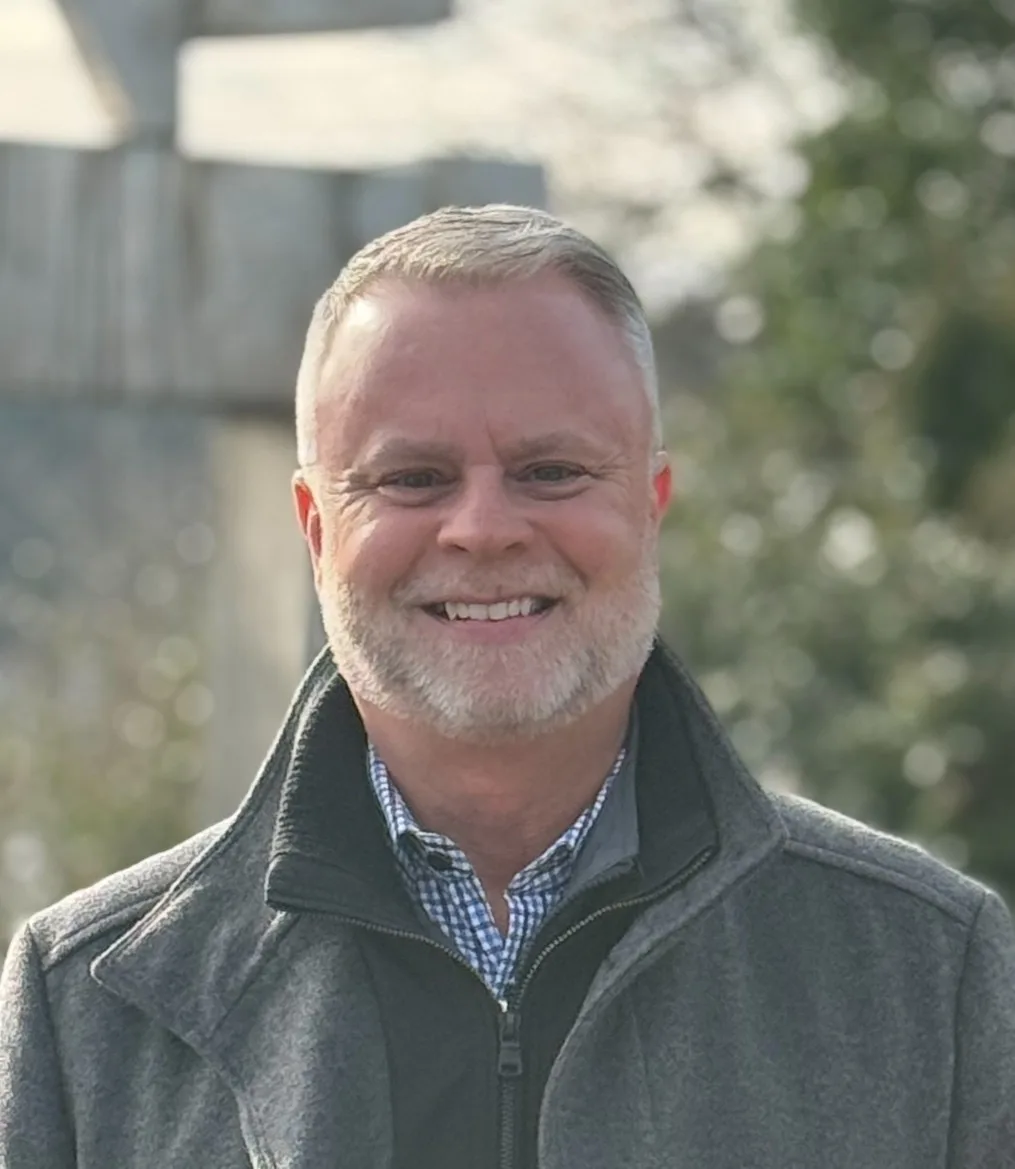
Travis Olson
Eureka Mortgage Planning
Northwest Area Manager · Based in Lake Oswego, Oregon
Financing is personal, and so is the guidance. Travis takes the time to understand your numbers, your timeline and your goals before recommending anything, and there is never pressure to move faster than you are ready. Every conversation ends with a clear next step, and all contact for Travis goes through the email below.
- Pre-approval support before you start touring
- Programs from conventional and FHA to VA, USDA, new construction and Non-QM
- Manufactured and modular home financing, in-park or land plus home
- Clear answers on eligibility and closing, no jargon
Start here
Why should you get pre-approved before you start looking?
Because the strongest buyer in this market is the one who shows up ready. Pre-approval takes the guesswork out of your budget and puts real weight behind every offer you write.
Eureka’s own guidance for buyers is exactly this: get pre-approved to learn the loan amount you qualify for, and you strengthen your position as a serious buyer before you ever write an offer. It takes a day or two of paperwork and a conversation with a lender, and it changes the entire feeling of house hunting: instead of wondering what you can afford, you know.
Talk to Our Mortgage PartnerYou know your real budget
Pre-approval narrows you to homes you can genuinely buy. No wasted weekends, no heartbreak over a house that was never in range.
Your offer carries weight
Sellers see financing risk as the main thing that kills a deal. A pre-approval letter says you are ready, so your offer lands differently.
You can move fast
Good homes in Bethany and Oak Hills do not wait around. Being approved means you can write a serious offer the same day the right house appears.
You keep emotion in check
When you already know your number, the search stays about fit, not anxiety about whether you could ever afford it.
The path to closing
How does the mortgage process work?
It looks intimidating from the outside; in practice it is six clear steps, and you will have help at every single one. Here is the whole path, start to keys, and Travis walks Bethany & Oak Hills buyers through it in plain English.
- 1
Application
You submit basic information about your income, assets, employment and the loan you want. This can often be started online in a single sitting.
- 2
Documents
The lender asks for the paperwork that proves what you told them: pay stubs, W-2s or 1099s, tax returns, bank statements and a copy of your ID.
- 3
Pre-approval
Once the lender verifies your documents, you receive a pre-approval letter stating the loan amount you qualify for. This is the letter your agent attaches to an offer, and it is what tells you which homes are really in reach.
- 4
Rate lock
When you are under contract, or close to it, you can lock an interest rate for a set period so your payment stays predictable while the loan processes. Ask your lender about the specifics of their lock options.
- 5
Underwriting
The lender does the deep review: the property appraisal, your credit and every document get a careful second pass. You may get a few follow-up requests here, and the fastest way through is to respond quickly.
- 6
Closing
You review and sign the final loan documents, settle closing costs, and take the keys. Your agent and your lender walk you through every signature.
Loan types, plainly
What loan options are available?
There is no single best loan; the right one depends on your situation. Below is the program lineup Travis Olson works with at Eureka Mortgage Planning, described straight. Rates and terms change with the market and with your personal picture, so we never quote numbers on a website: Travis will give you the honest, current specifics for you.
Conventional
The most common type, with flexible down payment options. Many conventional loans start around 3% down, and lenders assess your income and employment history to confirm your ability to repay. Solid credit history and income put you in the strongest position.
FHA
A government-insured program that is a popular route for first-time buyers. FHA loans commonly require around 3.5% down and generally allow lower credit minimums (commonly around 580), which makes homeownership reachable for more buyers.
VA & USDA
VA loans serve eligible veterans, active-duty service members and eligible surviving spouses, with benefits that can include no down payment. USDA loans serve eligible homebuyers in qualifying areas, also with 0%-down options for those who qualify.
Down payment assistance
Programs that help bridge the gap to your down payment and closing costs. Some buyers can combine assistance with another program to reach as little as 0% down. Availability depends on the program and on your eligibility, so it is always a conversation, not a guess.
New construction
Built for buyers purchasing a newly built home, including single-close construction and permanent financing in one loan. Eureka’s guidance is to get pre-approved for the entire loan amount before the building conversation starts.
Manufactured & modular
Financing for manufactured and modular homes, new or pre-owned, single- or multi-section, whether home-only in a park or land plus home. Available for primary residences and second homes, with programs starting around a 550 FICO.
Non-QM: bank statement, DSCR & more
For borrowers who do not fit standard program guidelines: bank statement loans, DSCR loans and other solutions built for retirees, high-net-worth borrowers and recent business owners. Program details vary by lender and are disclosed with a quote.
The honest note: the loan that fits your neighbor may not fit you. Travis works with a network of national and boutique lenders, so he can match buyers with the right program instead of pushing a one-size loan. He guides Bethany & Oak Hills buyers through pre-approval and eligibility, working with Paul Knighton and Chris Hayes so the loan conversation and the home search stay in step.
Paperwork, de-mystified
What do I need to apply?
The typical application asks for proof of income, two years of tax history, recent bank statements and a photo ID. Keep the list here in one folder and the whole process moves faster.
Do not worry about having it perfect. Your lender will tell you exactly what is needed, no guesswork, and we will make sure you know what to expect at each step.
-
Proof of income
Recent pay stubs, usually the last 30 days, plus W-2s or 1099s for the last year or two.
-
Tax returns
Usually the last two years, including business returns if you are self-employed or own a business.
-
Bank statements
Typically the last two to three months for every account you plan to use for down payment and closing.
-
Identification
A copy of your driver’s license or passport.
-
Extras that speed things up
Statements for retirement or investment accounts, and documentation for any large or unusual deposits. If you are self-employed, your profit-and-loss picture matters more than your pay stubs.
Financing FAQ
What do buyers ask about financing?
The questions buyers ask us before the first application, in plain English. Specifics always depend on your situation, and Travis will take it from here.
1 How much do I need for a down payment?
It depends on the program and on your eligibility. The program lineup Travis works with includes options that allow as little as 0% down, including down payment assistance, VA and USDA for eligible buyers. FHA loans commonly require a down payment around 3.5%, and many conventional loans start around 3%. The right answer for you depends on your qualifying picture, so Travis will give you the honest range for your situation, never a website number.
2 What credit score do I need to qualify?
As general program guidance: many conventional loans start around a 620 minimum, with scores above about 740 typically qualifying for better pricing; FHA loans commonly allow a minimum around 580; and manufactured-home programs are available from about 550. Non-QM program minimums vary by lender and are disclosed with a quote. Exact thresholds always depend on your full financial picture.
3 What is the difference between pre-qualification and pre-approval?
Pre-qualification is a quick estimate based on what you tell a lender. Pre-approval means your documents were actually reviewed and you hold a written commitment to an amount. Eureka’s guidance for buyers is to get pre-approved so you know the loan amount you qualify for, which strengthens your position as a serious buyer when you write an offer.
4 Can I get pre-approved before I have found a home?
Absolutely, and it is the order Travis recommends. He can pre-approve you for the loan amount you qualify for before you start touring, so every home you see is genuinely yours to pursue. For new construction, Eureka recommends being pre-approved for the entire loan amount before you begin the building conversation.
5 Do you help with new construction purchases?
Yes. Eureka Mortgage Planning offers new construction loans, including single-close construction and permanent financing in one loan. The guidance is to get pre-approved for the full loan amount first, then work with Travis and your builder so the financing and the build stay on the same timeline.
6 Can I finance a manufactured or modular home?
Yes, this is a specialty of Travis’s company. Financing is available for manufactured and modular homes, new or pre-owned, single- or multi-section, whether home-only in a park or land plus home, and for primary residences or second homes. Program availability starts around a 550 FICO, subject to eligibility.
7 What if I am self-employed or do not fit the standard box?
You still have real options. Travis works with Non-QM programs including bank statement loans, DSCR loans and other solutions designed for retirees, high-net-worth borrowers and recent business owners. Because these programs vary by lender, the specifics are disclosed with a quote rather than a generic number.
8 When should I get pre-approved?
Before you start touring in earnest. Knowing your number means every home you see is genuinely yours to pursue, and when the right one appears you can write a serious offer the same day instead of waiting on paperwork. It is the strongest position a buyer can start from.
No pressure, ever
Why is financing personal, and why does it matter?
Buying a home and financing it is one of the most personal decisions you will make, and every buyer’s numbers are different. Paul Knighton and Chris Hayes work with Travis to connect buyers with clear mortgage guidance at the right moment in the process. Tell us where you are in your timeline and we will make the introduction, or reach Travis directly; either way, there is no obligation and no pressure.
Ready when you are
Your next step starts with a conversation
Whether you are pre-approval-ready or just wondering what your number looks like, a short conversation gets you a straight answer. Email Travis, or ask us to make the introduction.